Today’s Sponsor
Elon Musk got full access to every federal budget, every agency, every line item — and what he found should terrify every American with savings. The U.S. spends $1 trillion a year on interest alone, 70% of the budget is legally untouchable, and even firing every federal employee wouldn't close the gap. Gold is already responding — up 95% in a year to $5,150. The math is broken, and no one in Washington is going to fix it.
We've put together a free report — "Breaking Point: Musk" — revealing exactly what Musk uncovered, why it's unfixable through normal means, and the one move retirees are making right now to protect themselves. If Musk couldn't fix it, your financial plan shouldn't depend on someone else fixing it either.
Download Your Free Report NowThis is an advertisement from American Alternative Assets. © American Alternative Assets. All rights reserved. If you no longer wish to receive promotions, please unsubscribe here or write to: 21550 W Oxnard St Ste 845, Woodland Hills, California 91367.

Markets hate uncertainty until they can price it. Today you’ve got political stalemate abroad, party fracture at home, a crypto shock that will rewrite risk controls, and one mega-cap selling a moonshot with real math behind it.
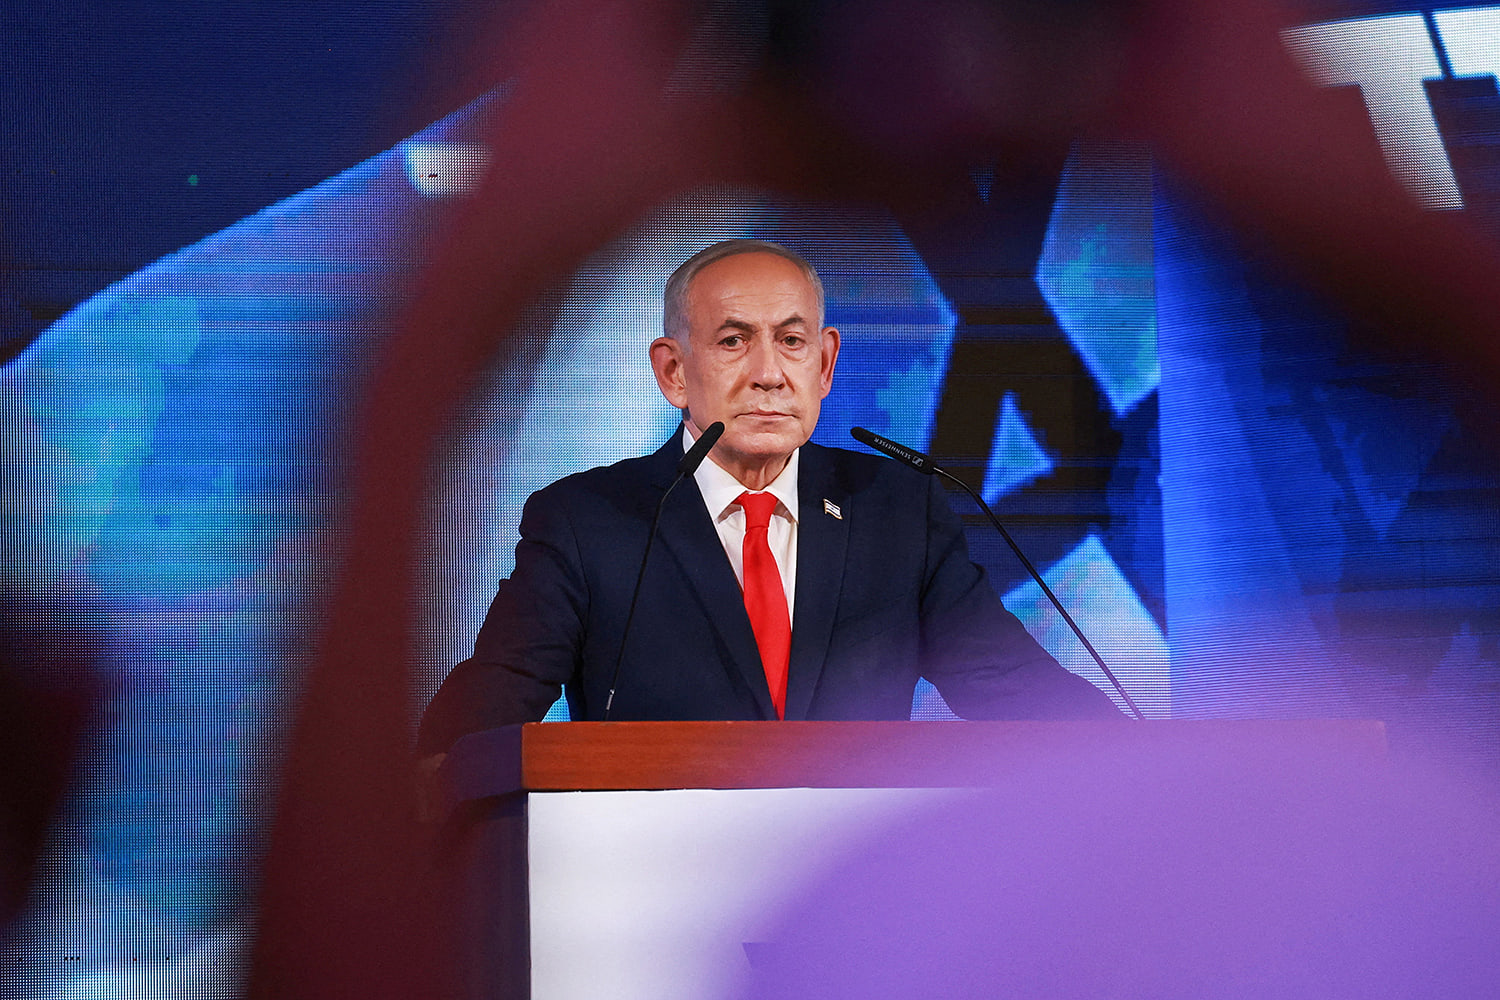
Image via NBC News
Israel election ends in a draw — kingmaker math shifts as Arab parties surge
Israel’s final results land with no clean governing majority for Netanyahu or his main rival. Same movie, new cast: coalition arithmetic, horse-trading, and the clock running while security and budget decisions sit on ice.
The headline inside the headline is the historic jump for Arab-minority parties, combining for 19 seats on record turnout among Palestinian citizens of Israel. That changes the coalition map. Even if they don’t join a government formally, they can influence confidence votes, budget priorities, and the political cost of certain policies.
Expect a period of political paralysis where everyone postures and nobody spends political capital. Markets can live with drama; they struggle with delayed decisions when the region’s risk premium is already elevated.
📈 Fred's Take: Israel risk is usually priced through energy, defense, and FX. Gridlock is not automatically bearish for Israeli assets, but it keeps a fat risk premium on the shekel and local rates because fiscal and security policy gets harder to execute. If you’re long regional risk, hedge it: oil calls, defense exposure, and don’t pretend the tail risk is gone just because the votes are counted.
📎 NBC News
Image via Fox Business
Binance hit for $6.3B — the crypto risk premium just repriced higher
Binance disclosed a security incident with an estimated $6.3 billion impact, with roughly $3 billion reportedly frozen. Translation: there’s still a giant pile of crypto plumbing that runs on trust, and trust is a lever that snaps fast.
This is bigger than one exchange. It’s stress on custody, cross-chain bridges, hot wallet procedures, and the entire assumption that “the infrastructure is mature now.” After something this size, every counterparty on every venue tightens limits, spreads widen, market makers pull back, and leverage gets repriced.
Watch second-order effects: stablecoin flows, perpetual funding rates, and OTC liquidity. The first move is panic; the real damage is the slow bleed as institutions step back and compliance teams slam the brakes.
📈 Fred's Take: Crypto’s problem isn’t price volatility — it’s operational fragility. After a hit like this, expect a sustained liquidity discount: wider spreads, lower leverage, and higher implied vols across majors. If you must be involved, own BTC as the cleanest collateral, keep assets off exchanges, and treat alt exposure like venture: small size, high expected failure rate.
Image via MarketWatch
Amazon’s two-trillion-dollar revenue dream: bold, not impossible, but the bar is brutal
Amazon CEO Andy Jassy told investors he sees a path to two separate businesses each doing $1 trillion in annual revenue. MarketWatch did the math off the Q3 print and the implied growth rates are the point: this isn’t a vibe statement, it’s a compounding statement.
To get there, you need sustained high growth at scale across commerce plus either cloud, ads, or something adjacent that becomes its own monster. That means Amazon must keep squeezing logistics efficiency, pushing retail take rates, and expanding ads, while AWS either re-accelerates or gets supplemented by new compute-driven demand.
The market question isn’t “can Amazon grow?” It’s “what multiple do you pay for a company that’s trying to compound into two mega-P&Ls while capex cycles and competition keep moving?”
📈 Fred's Take: Jassy’s target is a tell: Amazon is going to keep spending like a winner because the prize is platform dominance, not margin cosmetics. For investors, the setup is simple: if rates stay contained, the market will reward long-duration cash flow stories again and AMZN benefits. If rates back up, the multiple is the risk — not the business — so size it like a rate-sensitive compounder, not a defensive.

Image via The Hill
Democrats still fighting the last war — 2028 risk is policy whiplash, not personalities
Democrats are heading toward the next primary cycle with divisions still exposed after their 2024 loss. The Hill frames it as a preview of 2028: competing factions, competing messages, and a party trying to decide what it stands for when the base and the swing map want different things.
Markets should care because internal party conflict drives policy uncertainty. You get mixed signals on taxes, regulation, energy, trade, and antitrust depending on who’s winning the argument that week. That uncertainty filters straight into capex decisions and earnings guidance.
It also matters for the bond market: any credible push toward big new spending or big new taxes changes deficit trajectories and growth assumptions. You can’t price 2028 yet, but you can price the premium for instability.
📈 Fred's Take: The only thing markets hate more than a bad policy is a policy that keeps changing. A divided Democratic field increases the odds of messaging swings and late-cycle platform lurches, which means higher risk premium for regulated sectors and anything dependent on government demand. Own quality balance sheets, keep duration risk honest, and don’t fall in love with a “policy winner” trade until the nominee is real.
📎 The Hill

Image via National Review
California’s billionaire tax isn’t revenue — it’s a volatility machine
National Review calls California’s ballot “billionaire tax” an act of fiscal self-sabotage, arguing it will cost more than it raises. The core critique is behavioral: highly mobile capital doesn’t sit still for punitive, headline-friendly tax policy.
California already runs on a narrow base of high earners and capital gains. When you add a new levy on top, you’re not just taxing income — you’re increasing the incentive to shift domicile, shift realizations, and shift investment activity out of state. That doesn’t show up in the first-year projections; it shows up in the out-years when the base erodes.
If this passes, watch muni spreads, watch corporate location decisions, and watch the private markets ecosystem. It’s not “will people leave tomorrow?” It’s “will marginal decisions drift away steadily?” That’s how big tax bases die: one small choice at a time.
📈 Fred's Take: This is how you turn a cyclical revenue problem into a structural one. California doesn’t need more dependence on a shrinking, more mobile tax base; it needs stability so capital keeps building there. If you own California munis, demand a higher spread for political risk, and if you’re allocating to California-heavy venture and real estate, price in a slow leak of talent and taxable events.
That’s the tape. Price the uncertainty, respect the plumbing, and don’t overpay for duration if the bond market starts barking. — Fred Frost, Morning Bullets
— Fred Frost

