In partnership with

Anthropic IPO: how do traders get 2x the move?

Anthropic is going public, and GraniteShares is launching two 2x ETFs on it.
AIL → bullish, seeks 2x Anthropic’s daily move
ANS → bearish, seeks 2x the opposite
Anthropic +1% → AIL seeks +2%
Anthropic −1% → ANS seeks +2%
Built for traders who want to act on a short-term view of Anthropic, up or down, in one ticker, no margin needed.
Coming soon to your trading apps.
The fund does not invest in the underlying stock. Investment in these funds is not an investment in the underlying stock. Investment in these ETFs involve significant risk and are a short-term trading vehicle. Please go through the Prospectus and risk information before investing. Funds are distributed by ALPS Distributors, Inc. For important risk disclosures, learn more at https://graniteshares.com/

Pre-market read: fuel costs finally crack, Ukraine hits a symbolic artery, Trump flies into the Xi meeting with chips on the table, DOJ-politics heat up, and Treasuries remind everyone who actually sets the price of money.

Image via Axios
Diesel Slips Under $6: Quiet Win for the Real Economy
Average U.S. diesel prices dipped below $6 per gallon for the first time since early September. This is small on the screen, big in the supply chain. Diesel is the economy’s blood pressure: trucking, rail intermodal, construction equipment, farm machinery, and last-mile delivery all feel it fast.
Lower diesel is a margin story before it’s an inflation story. Freight-heavy businesses get relief immediately, especially anyone who couldn’t fully pass surcharges through. It also matters for the CPI narrative because diesel is a direct cost input that bleeds into goods prices with a lag.
Don’t over-celebrate: $5.99 is still historically expensive. But direction matters in markets, and diesel trending down is one of the few clean disinflation signals you can actually touch.
📈 Fred's Take: This is a tailwind for transports and industrials, not a reason to chase oil shorts. If diesel keeps sliding while demand holds, it’s a stealth boost to earnings for retailers, logistics, and construction names that have been eating cost pressure for months. Watch it against the bond tape: if rates stay ugly, cheaper diesel won’t save multiples, but it will cushion margins.
📎 Axios
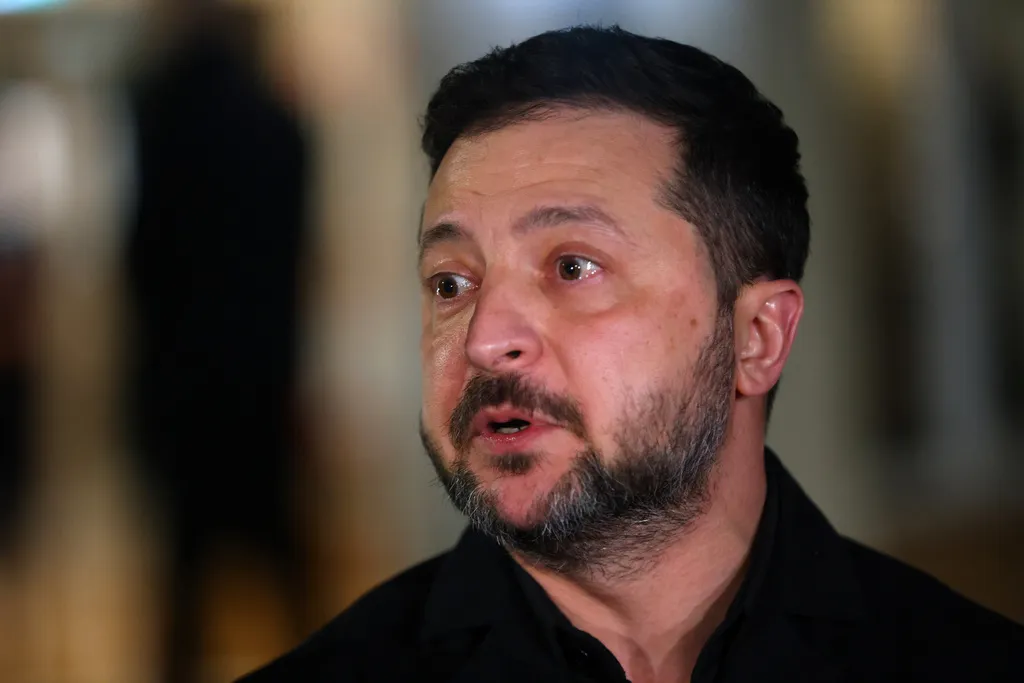
Image via Washington Examiner
Ukraine Hits Kerch Bridge: The War Just Repriced the Risk Premium
Ukraine launched record overnight strikes, including attacks targeting the Kerch Bridge linking Crimea to mainland Russia. That bridge is logistics, symbolism, and propaganda all rolled into one. Every time it gets hit, markets relearn the same lesson: the conflict can still escalate and it can still disrupt.
The immediate market channel is energy and shipping risk. Even if barrels keep flowing, risk premia can reappear in crude, distillates, and insurance costs on regional transport. The second channel is defense and cybersecurity demand, because sustained long-range strike campaigns require sustained countermeasures.
The headline here isn’t one bridge. It’s the shift toward higher-tempo, longer-range operations that make retaliation pressure rise.
📈 Fred's Take: Geopolitical shocks matter most when positioning is complacent. If crude has been leaning heavy on “demand slowdown” and “diesel easing,” this is the kind of catalyst that snaps that narrative for a few sessions. I’d treat energy volatility as back, keep some exposure to defense, and don’t get cute being short risk when the war tape is accelerating.
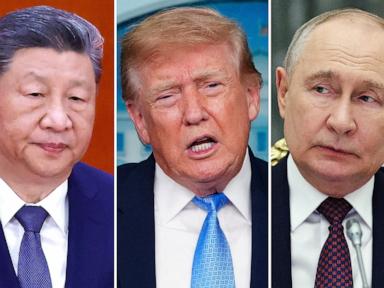
Image via ABC News
Trump Heads to Asia for Xi Meeting: Chips, Trade, and a Volatility Window
Trump is heading to Asia for a second high-stakes meeting with China’s President Xi. The trip lands with markets hypersensitive to anything that touches semiconductors, export controls, and supply chains. ABC notes questions circulating about the Nvidia CEO’s relationship with an alleged Chinese spy — exactly the kind of headline that turns tech policy into a trading event.
In this market, diplomacy isn’t about photo-ops. It’s about whether the next policy memo tightens or loosens the flow of high-end compute, and whether tariffs or restrictions get used as leverage. That directly hits mega-cap tech, the entire AI hardware stack, and any company that sells into China or builds in China.
Expect the rumor mill to front-run the meeting. Options will price it before the speeches do.
📈 Fred's Take: This is a headline-driven vol trade around semis and megacap tech, period. If you’re long the AI complex, you hedge into the meeting because one bad line about exports or “national security” can gap the whole group. If you’re looking for opportunity, the best setups are usually in the second derivative: suppliers and adjacent names that get dragged with the headlines but have less direct China exposure.
📎 ABC News
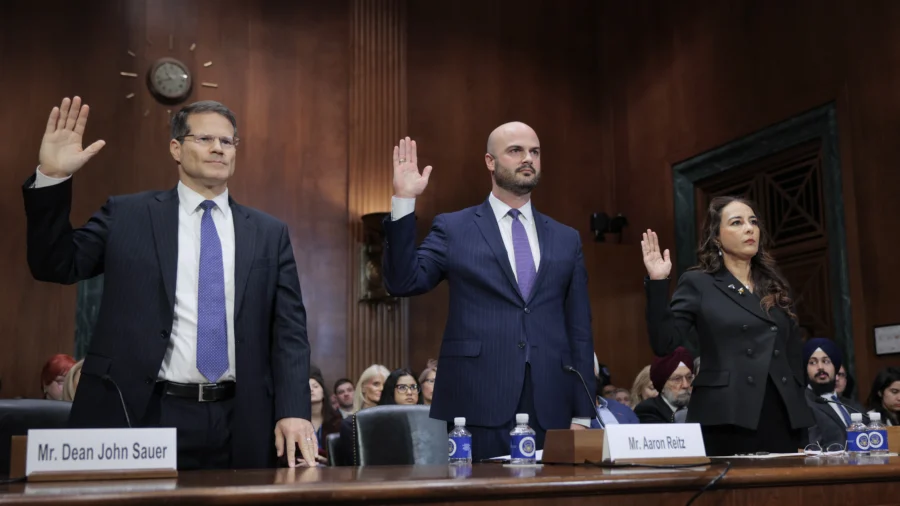
Image via NTD
DOJ Warning Shot at Warren: Politics Collides with Enforcement Again
A U.S. attorney is warning Sen. Elizabeth Warren against targeting Trump associates, adding fresh heat to the already messy intersection of politics and law enforcement. These fights don’t stay contained. They spill into confirmation battles, agency leadership, enforcement priorities, and the tone of regulatory risk for whole sectors.
For markets, the key is uncertainty around how aggressively Washington will pursue investigations, sanctions, and corporate actions tied to politics. That uncertainty changes behavior: companies slow decisions, donors harden positions, and regulators get pressured to make examples. It also becomes another brick in the wall of “governance risk premium” that investors demand to hold U.S. political exposure.
This is the kind of story that doesn’t move the S&P in five minutes but absolutely moves the probability distribution over the next year.
📈 Fred's Take: Investors should treat this as noise until it becomes policy, but don’t ignore the drift: rising political-legal conflict raises tail risk and makes bipartisan deals harder. The practical portfolio implication is to expect more headline volatility around defense, tech regulation, and anything adjacent to investigations. When politics turns into enforcement theater, the market trades fear first and facts later.
📎 NTD
Bond Bloodbath Returns: Ugly Inflation + Bad Auctions = Higher-for-Longer Repriced
Treasury yields snapped back after ugly inflation data and rough 10-year and 30-year auctions, with the government selling $766 billion in a heavy week of supply. Weak auction demand is the purest message the market can send: price me higher or I won’t show up. When the long end wobbles, everything else has to adjust.
This is not academic. Higher yields tighten financial conditions, hit housing affordability, raise corporate borrowing costs, and compress equity multiples. The long bond is the discount rate for growth stocks and the funding rate for leveraged everything. If auctions stay sloppy, you’re looking at a regime where the Treasury market forces policy credibility, not the other way around.
The risk is feedback: more supply, higher yields, larger interest expense, even more supply. That’s the loop equity bulls keep pretending doesn’t exist.
📈 Fred's Take: This is the tape you respect. If long rates are rising because buyers are balking, you don’t pay peak multiples for long-duration equities and you don’t pretend “soft landing” fixes the math. I want cash yielding real money, I want quality balance sheets, and I want to be picky on growth until the 10-year and 30-year stop acting like a broken auction machine.
That’s the grid. Trade what matters: diesel for margins, war for volatility, China for semis, DC drama for tail risk, and the bond market for the price of everything. — Fred Frost
— Fred Frost

