Today’s Sponsor
Trump declared "I'm a gold person" — and set off a chain of events most Americans are completely unprepared for. Gold just overtook U.S. Treasuries as the world's #1 reserve asset for the first time in 30 years. Central banks are buying at double the pace of the previous decade. And with the Treasury now expanding long-dated bond purchases, one top fund manager says bluntly: "That sounds like QE to me — and gold likes that too."
What does this mean for your retirement account? The rules of the next economy are being written right now — and if you don't know what's coming, you could be left behind. Get the full details before this window closes.
Get the Free ReportIf you would like to unsubscribe from receiving offers for Anchor Point Research, please click here. Or write to: 351 Paseo Nuevo, Floor 2, Santa Barbara, CA, US 93101.

Thursday, October 29, 2026: Courts are shaping election risk premiums, the FTC is coming for "surveillance pricing," delivery giants flirt with a merger, Russia escalates civilian-targeted drone terror, and Venezuela still can’t finish the handoff investors keep betting on.
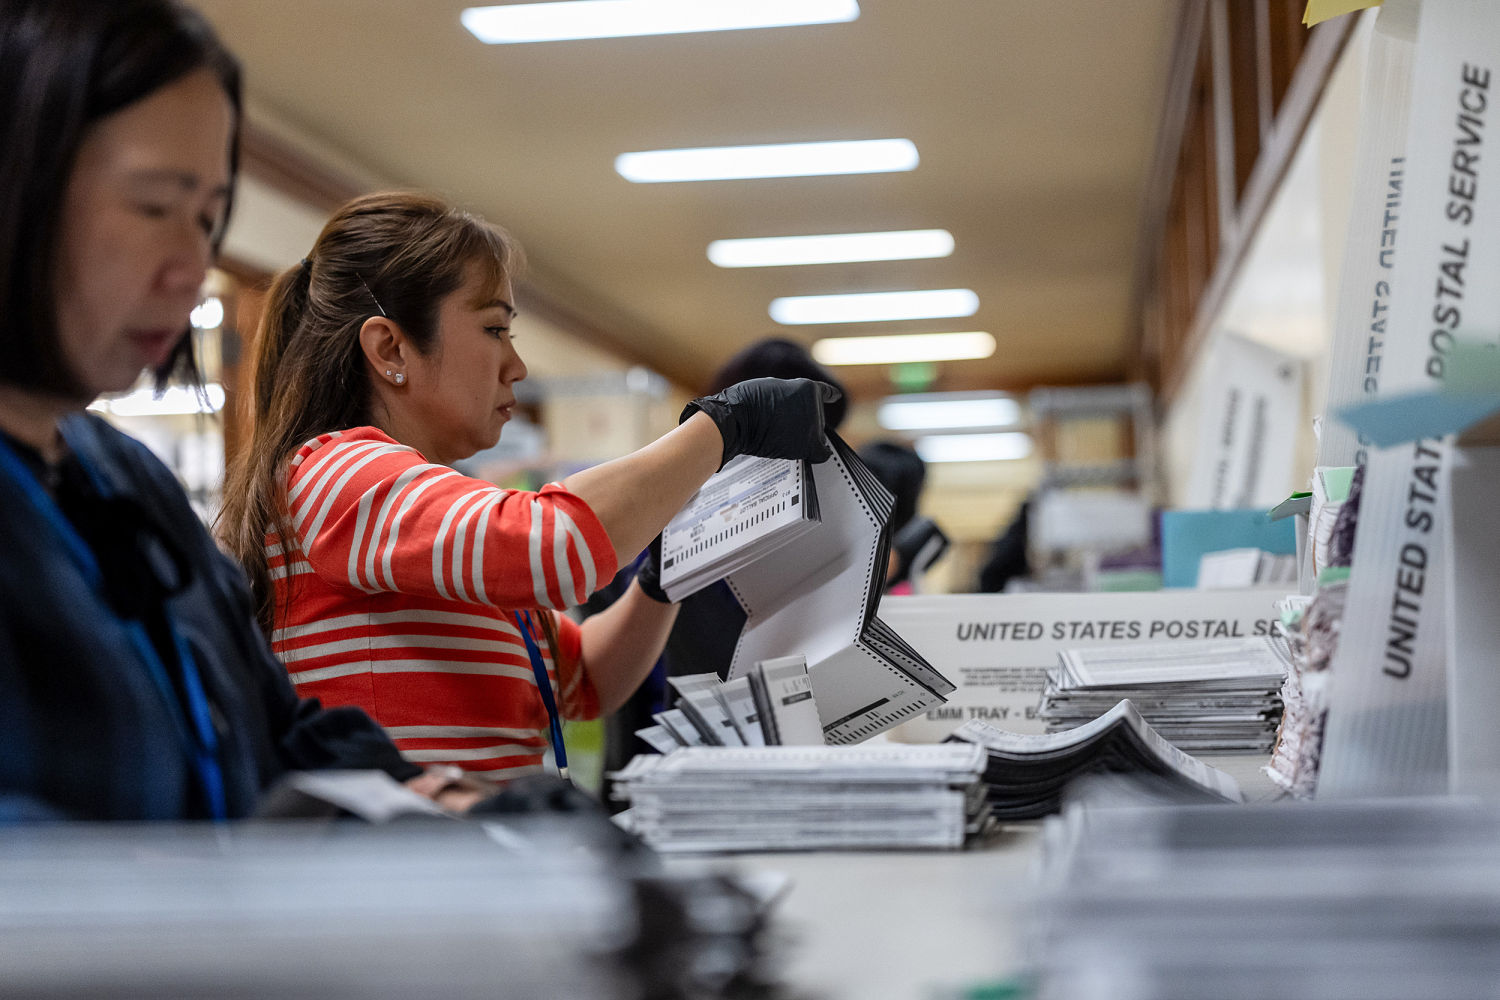
Image via NBC News
Judge blocks DOJ bid to quarantine 20,000 California ballots
A federal judge in California denied the Trump Justice Department’s request to segregate roughly 20,000 mail-in ballots tied to voters the administration alleges are noncitizens. Translation: the court refused to create a parallel ballot pool on DOJ say-so, at least on this record and on this timeline.
This matters because segregation orders are not just procedural. They’re a litigation accelerant. They turn routine election administration into a high-volatility event with a clear visual: a pile of “questioned” votes. The judge just made that visual harder to manufacture, which lowers the odds of a fast-moving, market-spooking escalation in the immediate term.
But don’t confuse “denied today” with “risk gone.” The broader theme is that election-adjacent legal fights are being pushed earlier and more aggressively. That keeps a political risk premium embedded in rates and USD vol, especially if we get more state-by-state injunction roulette.
📈 Fred's Take: Markets trade probabilities, not narratives. This ruling trims the near-term tail risk of an instant election-administration shock in California, which is mildly supportive for risk assets into year-end. The bigger trade is still volatility: keep an eye on USD and front-end rates because every new election-law filing is basically a gamma event with a headline trigger.
📎 NBC News
Image via Fox Business
FTC goes hunting for "surveillance pricing" across Delta, Uber, Walmart and more
The FTC ordered nine major companies to explain whether they use personal data to charge different customers different prices. Call it “surveillance pricing,” call it “personalized offers,” call it what you want: the regulator is signaling it wants to see the plumbing behind algorithmic pricing and targeting.
If this turns into enforcement, the impact isn’t just fines. It’s margins. Dynamic pricing is a quiet profit lever in travel, retail, mobility, and delivery. If the FTC forces disclosures, limits data inputs, or treats certain practices as unfair or deceptive, you’re looking at a structural hit to pricing power and customer lifetime value models.
The second-order effect is on the data supply chain: brokers, identity resolution, ad-tech, and the analytics vendors who sell “propensity” and “willingness-to-pay” scoring. When regulators push here, companies don’t just tweak a price tag. They re-architect systems, and that’s a multi-quarter capex and compliance drag.
📈 Fred's Take: This is a margin risk masquerading as a consumer protection story. If the FTC gets traction, expect multiple compression in consumer-facing names that lean on black-box pricing, and a chill across ad-tech data pipes. The trade is simple: pricing power is an asset until a regulator calls it discrimination by spreadsheet.
Image via MarketWatch
DoorDash and Instacart talk marriage; antitrust lawyers smell a long engagement
DoorDash and Instacart are pushing the case that a merger helps smaller grocers compete and creates efficiencies in last-mile logistics. Wall Street hears “synergies.” Washington hears “market power.” Analysts are already floating the base case: an extended antitrust review.
In plain market terms, the deal is about density. More orders per route, better utilization, better take rates, and potentially more leverage over restaurants, grocers, and brands buying placement. That’s the very logic regulators tend to dislike, especially when the consumer experience is already defined by fees, surcharges, and opaque ranking.
Even if the merger ultimately clears, the process itself is costly: management distraction, delayed product roadmaps, and a cloud over partnership negotiations. Competitors use the review window to poach merchants, drivers, and enterprise clients while you’re stuck answering subpoenas.
📈 Fred's Take: The risk isn’t that the deal fails. The risk is time. An extended review is a slow bleed on momentum and a gift to rivals, and markets punish that with dead money multiples. If you’re trading this, you’re trading regulatory duration, not delivery growth.
Russia hits a crowded Dnipro station with a jet-powered drone; civilian targets, higher war premium
A jet-powered drone struck a crowded train platform in Dnipro, killing 13 and injuring others as passengers waited to board. This is not a battlefield headline. It’s a deliberate strike on civilian mobility and public confidence, designed to make daily life unlivable.
Escalations like this typically pull three levers at once: more Western air-defense shipments, more Ukrainian pressure for longer-range capabilities, and more Russian willingness to test red lines with asymmetric tactics. That mix raises the odds of supply-chain disruptions, infrastructure damage, and retaliatory cycles.
For markets, the immediate channel is risk premium, not just in Eastern Europe. It shows up in defense spending trajectories, energy security policy, insurance pricing, and the geopolitical bid under commodities. War doesn’t need to spread to reprice assets; it just needs to become less predictable.
📈 Fred's Take: This pushes the war back into the “tail risk with a bid” bucket. Defense and security spending stays sticky, and the floor under energy and industrial commodities gets firmer when civilian infrastructure becomes the target set. If you’re positioned for a clean disinflation glide path, this is a reminder: geopolitics can reintroduce noise fast.
📎 DW

Image via The Dispatch
Venezuela’s transition is still unfinished, and markets keep misreading the clock
Venezuela remains stuck in a partial transition that never quite completes: political openings that narrow again, negotiations that reset, and institutions that don’t rebuild fast enough to anchor durable investment. The result is a country that can dangle “normalization” without delivering the rule-set foreign capital needs.
The Dispatch frames it as an unfinished handoff with plenty of side currents, including U.S. politics and global energy dynamics. Every time oil prices rise or supply gets constrained elsewhere, Venezuela gets pulled back onto the board as a potential release valve. But the gap between “barrels in theory” and “investable barrels” is where investors get hurt.
The real constraint isn’t geology. It’s governance: contract enforcement, sanctions uncertainty, operational security, and who controls what on the ground. That uncertainty is why Venezuela stories repeatedly create headlines and rarely create reliable cash flows.
📈 Fred's Take: Venezuela is not a timing trade; it’s a legal and political regime trade. The market keeps trying to front-run a clean normalization that still isn’t structurally available, and that’s why the risk-adjusted returns are usually worse than they look on the oil-price chart. Treat it as optionality, not a base-case supply fix.
That’s the tape: courts shape volatility, regulators target margins, antitrust delays are a tradeable tax, war keeps a bid under hard assets, and Venezuela remains a headline that doesn’t settle into cash flow.
— Fred Frost

