Today’s Sponsor
That "Trump Bump" Social Security raise? Already gone. Medicare premiums, gas, groceries — they've swallowed every penny before it hits your account. Meanwhile, your benefits have already lost 13.7% of their purchasing power since 2016, and the system would need to raise checks by 15.7% just to break even. You're getting $81. You needed $296.
Central banks have been quietly buying one specific asset at the fastest pace in 50 years — and JP Morgan now sees it hitting $8,000. Smart retirees aren't waiting on the next COLA. They're protecting what's left right now. Get the free guide and see the 3 steps disciplined retirees are using to outrun the inflation Washington can't stop.
Get the Free Wealth Preservation GuideThis is an advertisement from First Ballot. If you no longer wish to receive First Ballot promotionals, please let us know. Or write to: 5005 Lyndon B. Johnson Fwy. Suite 350, Dallas, TX 75244

Monday, October 19, 2026. Markets are pricing a soft landing and a hard world. Today’s tape is about AI capex monetization, private-market theatrics, and the slow-motion re-rating of Europe and energy risk.

Image via Investing.com
Bernstein flips Datadog to Buy: AI observability is turning into a toll road
Bernstein lifted Datadog to Buy on the view that AI-driven workloads are creating stronger tailwinds for monitoring and observability. Translation: more compute, more microservices, more model endpoints, more things breaking at 3 a.m. Somebody has to meter it, alert it, and prove it worked.
Datadog’s story has always been usage. The bear case was spend compression when CIOs got religion about cloud bills. The bull case is that AI doesn’t simplify stacks, it multiplies them. If the next wave of enterprise software budgets is “keep the models up and compliant,” DDOG sits right in the blast radius.
Watch the second-order numbers: net retention, log ingestion growth, security modules attach, and whether management can talk about AI-native customers without hand-waving. This name trades like a high-duration asset, so the setup is simple: any hint of re-accelerating usage gets you multiple expansion, and any macro wobble brings the guillotine back.
📈 Fred's Take: This is the cleanest way to play AI without pretending you can pick the winning model. The money is in the picks-and-shovels that get invoiced every month. I’d rather own the toll collector than the gold miner, and DDOG is a toll collector with leverage to AI chaos.

Image via Forbes
Musk says he’ll give every U.S. child a SpaceX share: meme policy meets private-market reality
Elon Musk says he’ll give every child in America one SpaceX share next year, a headline engineered to detonate across social feeds. It landed right after he criticized Anthropic’s idea to dedicate 5% of shares to a public benefit fund, pushing instead for broader public distribution.
Here’s the friction: SpaceX is private, tightly held, and cap-table mechanics aren’t a tweet. Who is issuing the shares, at what valuation, with what tax treatment, custody, transfer restrictions, and securities law framework? If this ever becomes more than a stunt, it turns into a regulatory and logistical monster.
Markets won’t price SpaceX directly, but they’ll price the vibes. Every time Musk does “capital markets theater,” you should expect spillover into Tesla sentiment, the broader space/defense complex, and the retail bid in anything that smells like access to private growth.
📈 Fred's Take: Treat this as marketing, not macro. The trade is sentiment: it reinforces the retail hunger for private-company exposure and increases pressure for more SPVs, tokenized equity wrappers, and late-stage IPO pipelines. If you’re positioned in anything dependent on sober governance, remember Musk optimizes for attention, not your drawdown.
📎 Forbes
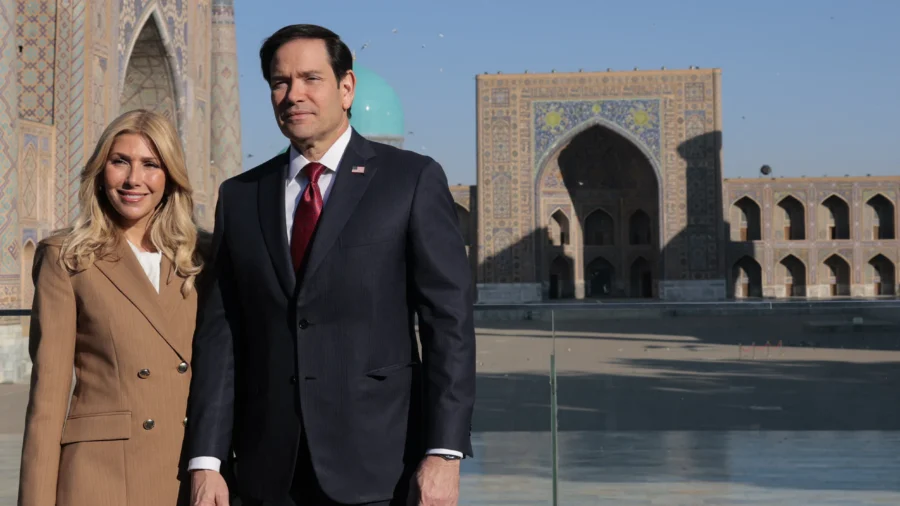
Image via NTD
Rubio in Uzbekistan: Washington is shopping for supply chains and energy leverage
Secretary of State Marco Rubio visited Uzbekistan as the U.S. looks to deepen ties in Central Asia. The photo-op is easy. The strategic target is harder: diversify logistics, minerals, and energy relationships away from Russian and Chinese choke points.
Central Asia sits on a map traders should respect. It’s a corridor for commodities, a chessboard for pipelines and rail, and a growing battleground for influence. If Washington is serious, you’ll see follow-through in export finance, infrastructure support, and security cooperation.
The market angle is incremental, not instant. Think longer-term de-risking: critical minerals supply, uranium flows, and the slow grind of building “friend-shored” routes that reduce tail risk in global production networks.
📈 Fred's Take: This is a geopolitical hedge masquerading as diplomacy. If the U.S. can pry open more reliable commodity and transit options, it’s mildly disinflationary over time and supportive for industrial metals planning. Don’t front-run headlines, but do keep an eye on uranium, copper, and defense-adjacent logistics plays tied to Eurasian corridors.
📎 NTD
Paris unrest drags on: Europe’s stability premium keeps leaking
A specialist urban violence police squad was deployed to Paris as riots and looting continued. Whatever your politics, the market reads this as governance stress, and governance stress raises the discount rate on everything tied to domestic confidence.
Europe can survive protests. What it can’t easily absorb is repeated episodes that hit tourism, retail, and small business sentiment while policymakers are already juggling growth stagnation and fiscal strain. When civil order becomes a recurring line item, capital quietly looks for calmer jurisdictions.
The near-term market reaction usually shows up in risk premiums: weaker consumer-facing earnings expectations, a firmer bid for safe assets, and a mild drag on the euro when investors sense political fragmentation.
📈 Fred's Take: This is not a one-day news trade; it’s a slow erosion of Europe’s “boring and safe” narrative. If you’re allocating internationally, you demand a bigger margin of safety on eurozone cyclicals and banks. In portfolios, this is another reason gold keeps its seat at the table and why U.S. assets keep getting the benefit of the doubt.
Putin pitches a Trump-Xi-Ukraine summit without Zelenskyy: markets hear “energy leverage” loud and clear
Putin reportedly proposed a three-way summit with Trump and Xi on the Ukraine war, excluding Ukraine’s President Zelenskyy. The headline matters less than the signal: Russia wants great-power bargaining, and it wants to reframe the war as an energy-and-security negotiation among superstates.
This lands amid mounting tensions between Ukraine and the United States. That’s the key input for traders: perceived Western unity is a pricing factor for crude, natural gas, European risk assets, and defense spending expectations. Any crack in alignment increases uncertainty, and uncertainty tends to show up first in energy.
If this track gains oxygen, expect a volatility bid in oil and European gas, a defensive tilt in European equities, and renewed attention on LNG flows and storage. Diplomacy headlines can reverse fast, but energy markets don’t wait for signed communiqués.
📈 Fred's Take: Excluding Zelenskyy is the tell: this is leverage, not peace. The market risk is mispricing a “deal” narrative and then getting hit by reality when talks stall or terms prove politically impossible. Position for headline whipsaws: keep energy hedges tight, don’t chase risk-on Europe, and assume defense outperformance persists as long as the security order is contested.
📎 CNBC
That’s the board. Respect the tape, hedge the headlines, and don’t confuse viral narratives with tradable fundamentals. Fred
— Fred Frost
